
New Delhi, India — March 23, 2026
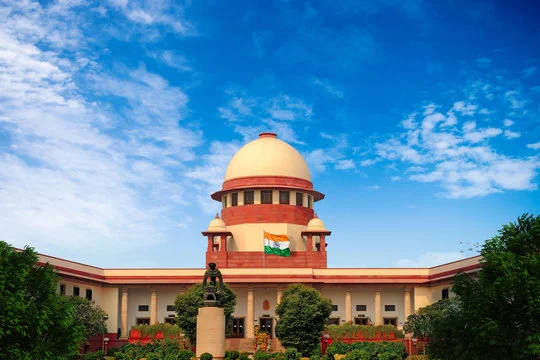
India’s Supreme Court has ruled that consumer forums cannot adjudicate banking disputes involving allegations of fraud and forgery, reinforcing the need for such cases to be addressed through civil or criminal courts.
The ruling comes in the case of Sant Rohidas Leather Industries vs Vijaya Bank, where the court examined whether disputes related to unauthorised pledging of fixed deposits could be resolved under consumer protection laws.
The bench, comprising Justices PS Narasimha and Manoj Misra, held that consumer forums, which operate under summary procedures, are not equipped to handle complex cases involving detailed evidence and criminal allegations.
The dispute originated from a ₹9 crore fixed deposit placed by Sant Rohidas Leather Industries with Vijaya Bank in 2014. The company alleged that the bank had fraudulently created an overdraft facility of ₹8.1 crore against the deposit without consent and later adjusted the deposit proceeds to settle the overdraft.
The company sought a refund of the deposit along with interest, citing deficiency in service. However, the bank argued that the deposit had been validly pledged to secure credit facilities and that the case involved serious allegations of fraud and forgery.
The National Consumer Disputes Redressal Commission (NCDRC) had earlier dismissed the complaint, stating that the company did not qualify as a consumer under the Consumer Protection Act, 1986.
Clarification on Consumer Status and Jurisdiction
The Supreme Court clarified that companies can qualify as consumers under the law, depending on the nature and purpose of the transaction. It rejected the NCDRC’s blanket position that interest-bearing deposits automatically constitute commercial activity.
The court noted that depositing surplus funds with a bank for safekeeping or regulatory compliance does not necessarily amount to a commercial transaction. However, where such deposits are used to secure credit facilities, the transaction may take on a commercial character.
Despite this clarification, the court upheld the dismissal of the complaint, emphasising that allegations of fraud, forgery, and unauthorised transactions require detailed examination and cannot be resolved through summary consumer proceedings.
Implications for Banking Disputes and Risk Management
The ruling highlights a clear distinction between consumer protection mechanisms and judicial processes required for complex financial disputes. Cases involving alleged document fabrication, unauthorised pledges, or misuse of financial instruments will need to be pursued through appropriate legal channels.
This is particularly relevant for corporate banking relationships, where disputes often involve layered financial arrangements, credit facilities, and documentation that require extensive evidentiary review.
Industry Context: Legal Risk in Financial Transactions
The judgment comes amid increasing scrutiny of fraud risk, documentation integrity, and dispute resolution mechanisms in banking. As financial transactions become more digitised and interconnected, the ability to establish clear legal recourse pathways is becoming critical for both banks and corporate clients.
The decision also underscores the importance of robust documentation, consent frameworks, and internal controls in banking operations, particularly in credit-linked transactions involving deposits and collateral structures.
Digital Trade Outlook’s View: Supreme Court
Digital Trade Outlook Analysis
The ruling reinforces the growing importance of legal clarity and risk management in financial transactions linked to trade and corporate banking. As trade finance structures become more complex, disputes involving collateral, guarantees, and financing arrangements are likely to require formal judicial processes rather than summary resolution mechanisms.
Related on Digital Trade Outlook
- India’s Major Ports Handle 915 Million Tonnes in FY26, Exceed Annual Target
- IndusInd Bank Rolls Out New Banking Vertical Focused on India’s GCCs
- CommBank Deploys AI Agent to Detect Emerging Fraud Patterns in Real Time